Charging a company car at home: billing rules in Austria from 2026
Since 2026 the €30 monthly flat rate is gone. Reimbursement stays tax-free only if the charged energy can be assigned to the company vehicle. What that means technically, and how the process works in practice.
What changed in 2026
Until the end of 2025 there was a transitional rule: if the charging equipment at home could not assign the charged energy to the company vehicle, the employer was still allowed to reimburse up to €30 per calendar month free of tax and contributions. That option expired on 31 December 2025.
Since then, a tax-free reimbursement for charging in a private setting is only possible if the charged energy can be demonstrably assigned to the employer-owned electric vehicle. Without that proof, the employer's payment counts as regular salary, subject to income tax and social security contributions.
For fleets with home charge points this is not a formality, but a technical requirement placed on the charging infrastructure.
The official electricity price for 2026
The Austrian Ministry of Finance sets the applicable electricity price each year, up to which the reimbursement remains free of tax and contributions. For the 2026 calendar year the rate is 32.806 cents per kWh (2025: 35.889 cents), the first decrease since the rule was introduced.
What this means in practice:
The rate is an upper limit, not a flat allowance. Without proof of the charged energy it does not apply at all.
The employee's actual electricity price is not relevant. If their own tariff is lower, the difference still remains free of tax and contributions.
If more than the official rate is reimbursed, the excess is subject to tax and social security contributions.
Worked example: A field sales employee charges 4,000 kWh at home over the year. At 32.806 cents per kWh, that adds up to a tax-free reimbursement of €1,312.24, provided those 4,000 kWh can be demonstrably assigned to the company vehicle. For comparison: at a public DC charging station costing around 76 cents per kWh, the same amount of energy would come to roughly €3,050.
NeuraCharge Calculator
Why a meter alone is not enough
This is where the real misunderstanding lies. Many companies assume that a wallbox with a built-in meter satisfies the requirement. But a meter only records how much energy flowed through the wallbox, not which vehicle drew that energy.
Typical situations in which this becomes a problem:
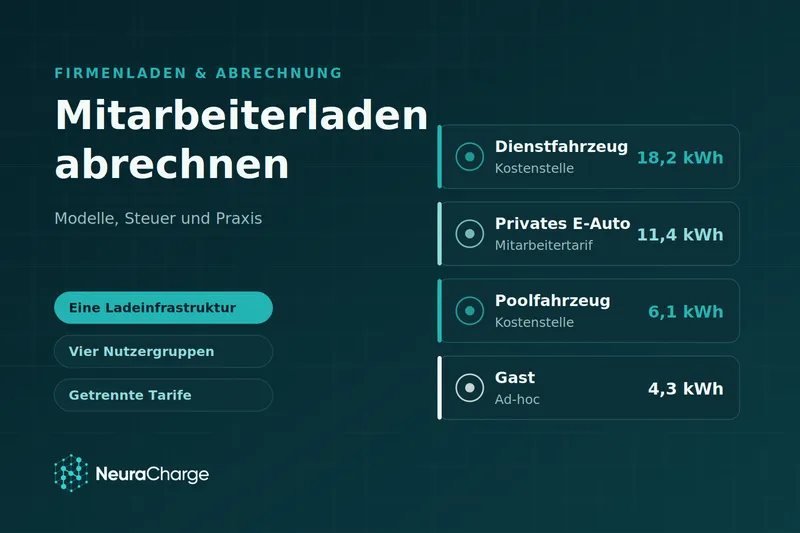
Alongside the company car, the household also has a private electric vehicle or a partner's car.
A second company vehicle is occasionally charged at the same wallbox.
The wallbox is used now and then by visitors.
The employee changes company vehicle during the year.
In all of these cases the meter reading is correct, but the assignment to the specific company vehicle is not. What is needed is user- and vehicle-based recording of every individual charging session, for example through RFID authorisation, app-based release or vehicle identification.
What a robust home charging settlement has to deliver
For the reimbursement to hold up under audit, five points should be covered:
Measurement at the charge point, either through a meter inside the wallbox or a separate meter. A MID-compliant measuring device is not explicitly required by law, but it is the de facto standard in practice and considerably easier to defend.
Assignment to vehicle and user, per charging session rather than per month.
Separation of private and business charging, cleanly at the level of the individual session, not via estimated allocation keys.
Documentation covering date, duration, kWh, charge point and user, valued at the official rate, as a traceable record.
Handover to payroll, monthly and automated, without collecting emailed photos of meter readings.
Point five is regularly underestimated. With five home charge points a spreadsheet still does the job. With fifty, it becomes a monthly process that ties up HR and fleet management permanently, and in which every manual transfer is a potential source of error.
You can find out more about this here too.
Charging with your own PV system
If the employee charges the company car with electricity from their own photovoltaic system, the logic does not change: what matters is the energy assigned to the vehicle, valued at the official electricity price. The origin of the electricity is not relevant to that valuation.
For employees with a PV system this is financially attractive, because self-consumption is valued more highly than feeding electricity into the grid. Here too, unambiguous assignment of the charged energy remains the precondition.
One caveat: the legal position on self-generated PV electricity is less clearly regulated in Austria than the standard case. For larger fleets it is worth clarifying this with your tax adviser.
What remains unchanged
Charging at the company site remains free of tax and contributions for employees, including for company vehicles that are also used privately.
Employers may contribute up to €2,000 towards home charging equipment without a benefit in kind arising.
Public charging can be reimbursed against a receipt.
Different rules apply to an employee's private electric vehicle: reimbursing those charging costs is subject to tax and contributions.
For fully electric vehicles, no benefit in kind applies until the end of 2026. From 1 January 2027, 0.375 percent of the gross purchase price is planned, capped at €180 per month. Anyone planning charging infrastructure now should factor that in.
Checklist for fleet managers
Which employees charge the company car at home?
Can the wallboxes in use assign charging sessions to individual users or vehicles?
Are there additional electric vehicles in the household?
How does charging data reach payroll today, and how long does that take each month?
Is there a traceable record for every charging session?
Is it defined what happens on a vehicle change, when someone leaves, or after a move?
If the answer is unclear in more than two places, the process should be set up before the next payroll run, rather than retrospectively once an audit is under way.
We also have a calculator for this to help you estimate the costs more accurately. Click here
Company car billing with NeuraCharge
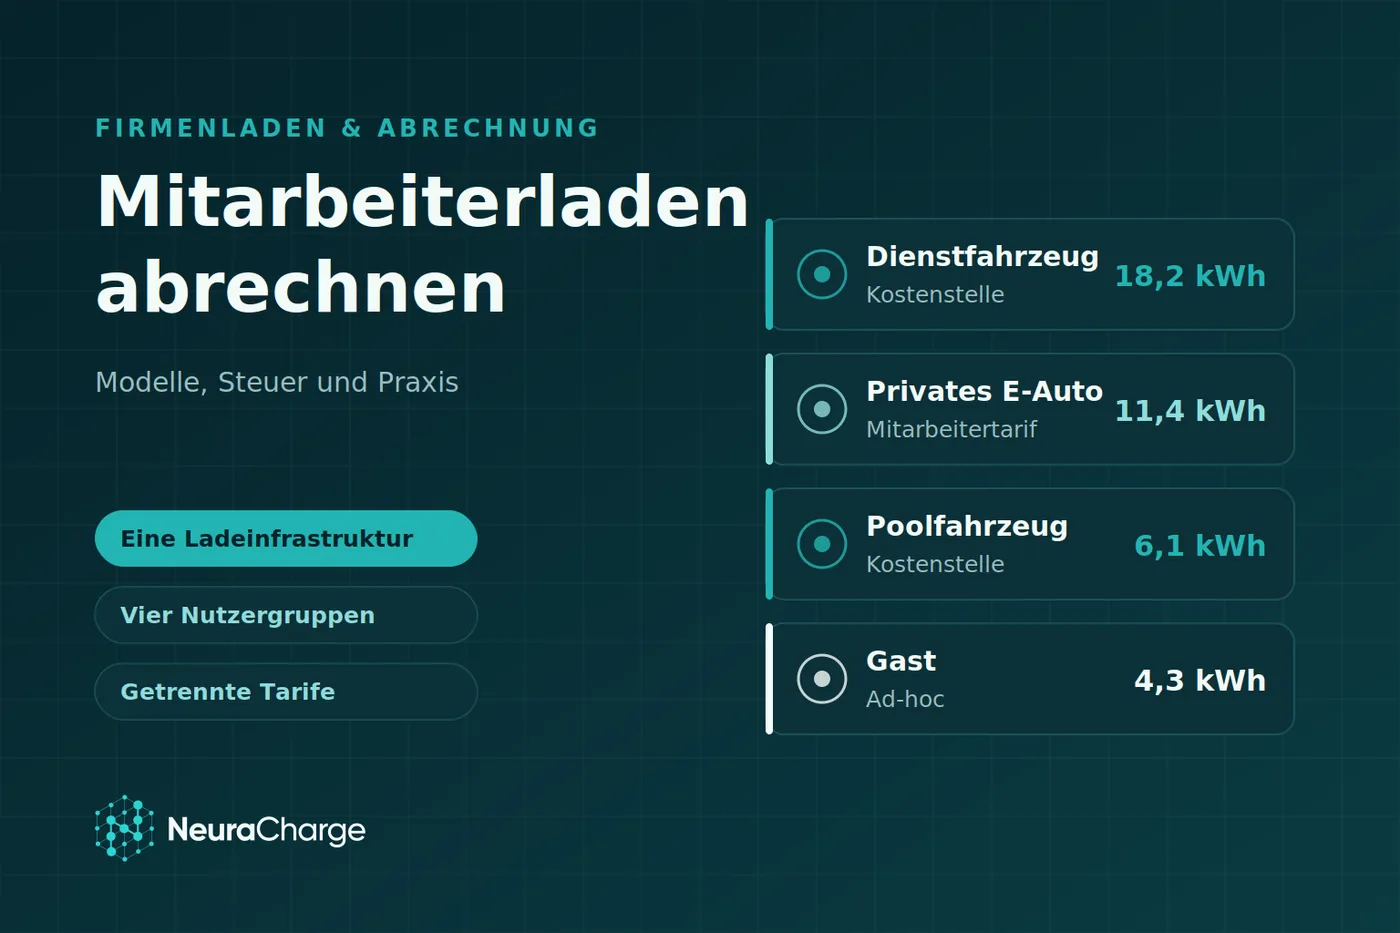
NeuraCharge records every charging session at the home wallbox and assigns it unambiguously to a vehicle and a person via user account or RFID. Private and business sessions are kept separate, even when several vehicles in the same household charge at the same wallbox.
Business charging sessions are automatically valued at the stored official electricity price and made available as a monthly statement: per employee, with individual proof for each session, exportable for payroll or passed directly into existing systems via interface.
Because NeuraCharge works independently of any manufacturer, it makes no difference which wallboxes are in use across the fleet. Mixed estates can be managed on a single platform, with charge points at the company site and home chargers appearing in the same evaluation.
For companies this means one process instead of individual workarounds, one record per employee per month, and evidence that holds up under audit.
Please note: this article provides general information and does not replace tax or legal advice. For an assessment of your specific situation, please consult your tax adviser.