Charging a company car at home: billing rules in Austria from 2026
Benefit in kind for electric company cars in Austria from 2027
Teaser: Austria's zero benefit in kind is ending. From 2027 it is 0.375 percent of the purchase price, from 2028 it is 0.625 percent. Vehicles already in the fleet are affected too.
What was decided
Until now the rule was simple: anyone allowed to use a fully electric company car privately paid nothing for that benefit. The benefit in kind was set at zero. It was the single largest tax advantage of electric mobility in Austria and a key reason why a substantial share of new electric registrations are company vehicles.
From 2027 this changes in two steps:
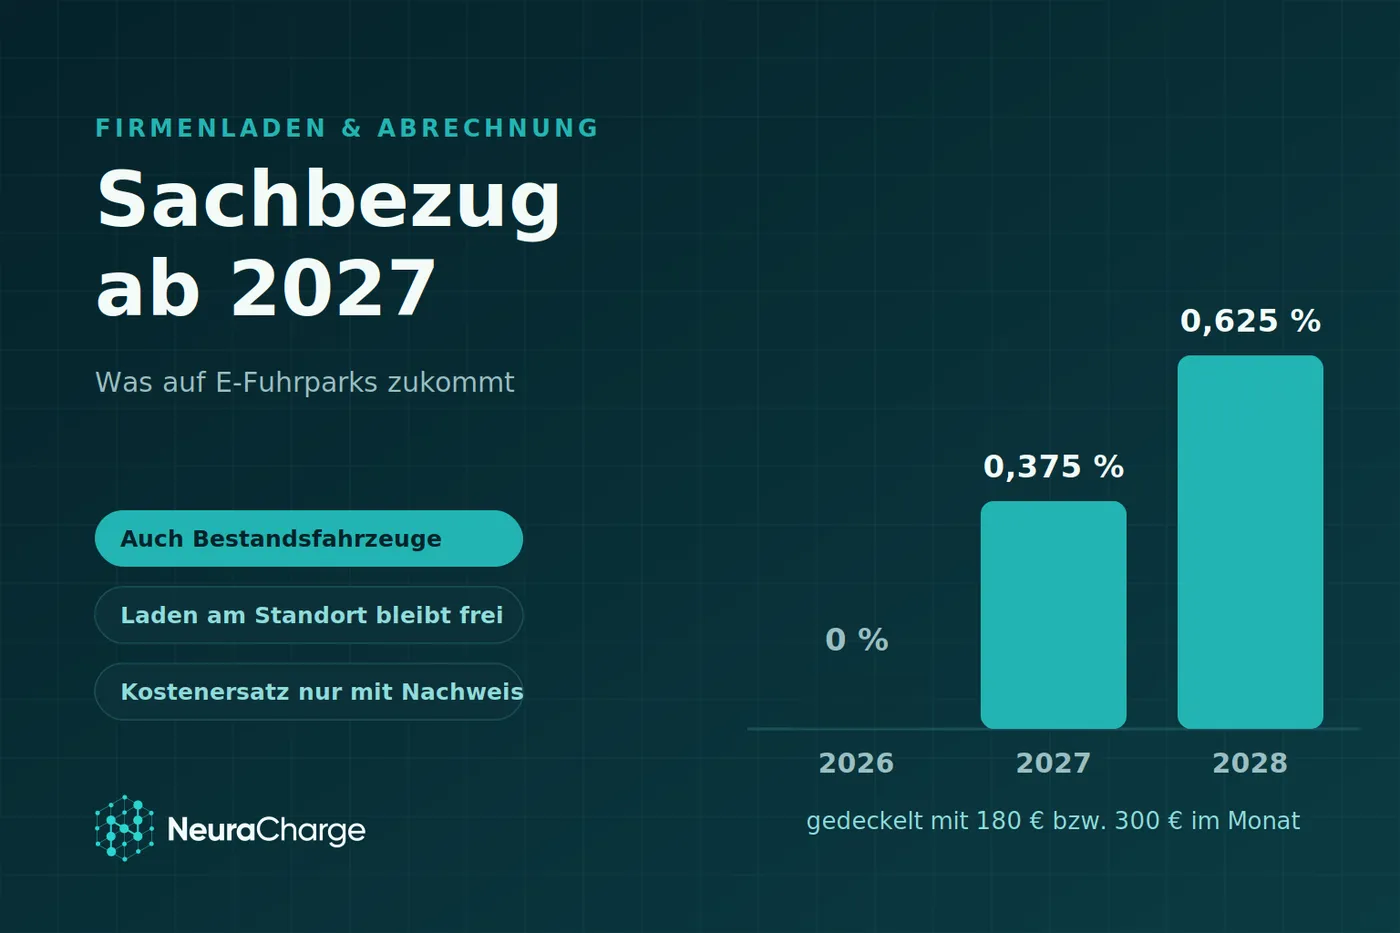
From 1 January 2027: 0.375 percent of the purchase price per month, capped at €180 per month.
From 1 January 2028: 0.625 percent of the purchase price per month, capped at €300 per month.
The basis of assessment is the purchase price including VAT and the Austrian standard fuel consumption levy (NoVA). According to the explanatory notes, no further adjustment is planned before 2030, when the effect of the rule is to be evaluated.
These figures apply to Austria. Germany uses an entirely different system, so the values here cannot be transferred across the border.
Existing vehicles are affected too
This is the point that will catch many fleets off guard. Whether a vehicle was newly registered or has been in the fleet for years makes no difference to whether a benefit in kind applies. From 2027 it applies to every electric company car made available to employees, provided private use is not excluded.
Anyone who electrified a fleet in 2025 on the basis of the zero benefit in kind should redo that calculation. It affects more than vehicle costs: commitments already made to employees come into play as well.
Worked example
A company car with a gross purchase price of €50,000:
2027: 0.375 percent works out at €187.50. The cap brings it down to €180 per month, so €2,160 per year.
2028: 0.625 percent works out at €312.50. Capped, that is €300 per month, so €3,600 per year.
This amount increases the basis for income tax and social security contributions. Depending on the individual tax bracket, employees will feel it in their net pay, and employers face higher ancillary wage costs.
What stays the same
Much of what makes an electric company car attractive remains untouched as things stand:
Charging at the company site remains free of tax and contributions for employees. This applies both to company vehicles and to employees' private electric cars charged at the site free of charge.
Reimbursement for charging at home remains possible, although since 2026 only where the charged energy can be unambiguously assigned to the specific company vehicle. The official electricity price for 2026 is 32.806 cents per kilowatt hour.
The wallbox contribution of up to €2,000 towards private charging equipment remains free of benefit in kind.
Input VAT deduction for electric passenger cars stays within the existing limits.
That shifts the balance. Once the benefit in kind advantage disappears, the quality of the charging infrastructure and of the billing process becomes the remaining lever companies have to keep an electric fleet attractive.
Where the legislation stands
The change was agreed as part of the Budget Accompanying Act for 2027 and 2028. At the time of writing, the final adoption of the amended Benefits in Kind Regulation was still pending. The headline figures are considered settled, but details may still shift before publication.
We will update this article once the regulation has been published.
What companies should do now
Run the numbers on the fleet. Which vehicles are made available for private use, and what benefit in kind does each of them produce from 2027?
Align with payroll. The benefit in kind has to be recorded from January 2027 onwards, including for existing vehicles.
Review the car policy. Where does a contract or company car scheme contain a commitment that relies on the zero benefit in kind?
Tell employees early. A change in net pay in January that nobody announced beforehand creates avoidable friction.
Check whether private use can be excluded. For pure pool vehicles, a demonstrably prohibited and monitored ban on private use may be relevant. The detail belongs with your tax adviser.
Get home charging billing in order. Cost reimbursement remains one of the few tax-free building blocks left, but only with complete evidence.
Where NeuraCharge fits in
The benefit in kind itself is a payroll matter. What NeuraCharge covers is the step before that: the clean recording and assignment of every charging session, whether at the company site, at a home wallbox or on the road.
Sessions are recorded per vehicle and per person, private and business use are kept separate, and a monthly statement is provided that can be handed straight to payroll. Those records are exactly what determines whether reimbursement for home charging stays free of tax and contributions.
If you are recalculating your fleet for 2027 anyway, it is worth looking at the billing process at the same time. The manual workarounds that coped with five vehicles rarely survive the new evidence requirements.
Please note: this article provides general information and does not replace tax or legal advice. For an assessment of your specific situation, please consult your tax adviser.